Streamlined Guides: K-Content – What A Hit Is Worth & To Whom

PART TWO: Who is paid when a Korean drama succeeds, where that leaves the industry now, and what the next three installments will cover
Editor's Note: This is the second installment in a series that looks at the Korean content industry – how it evolved, where it stands now and which business models it could be adopting in the future. The series is written by Jaden Jaebum Park, a director and producer at Korean broadcaster MBC, who between productions writes about the economics of content industries.
The first installment traced where Korean drama's strengths came from, set out the four conditions an industry needs to keep what it makes (velocity, protection, resilience, accumulation), and followed the money behind the work as it moved from the broadcasters to China and then to Netflix between 2014 and 2019. See below for the first installment.
 Jaden Jaebum Park
What A Hit Is Worth Now, And To Whom
By Jaden Jaebum Park
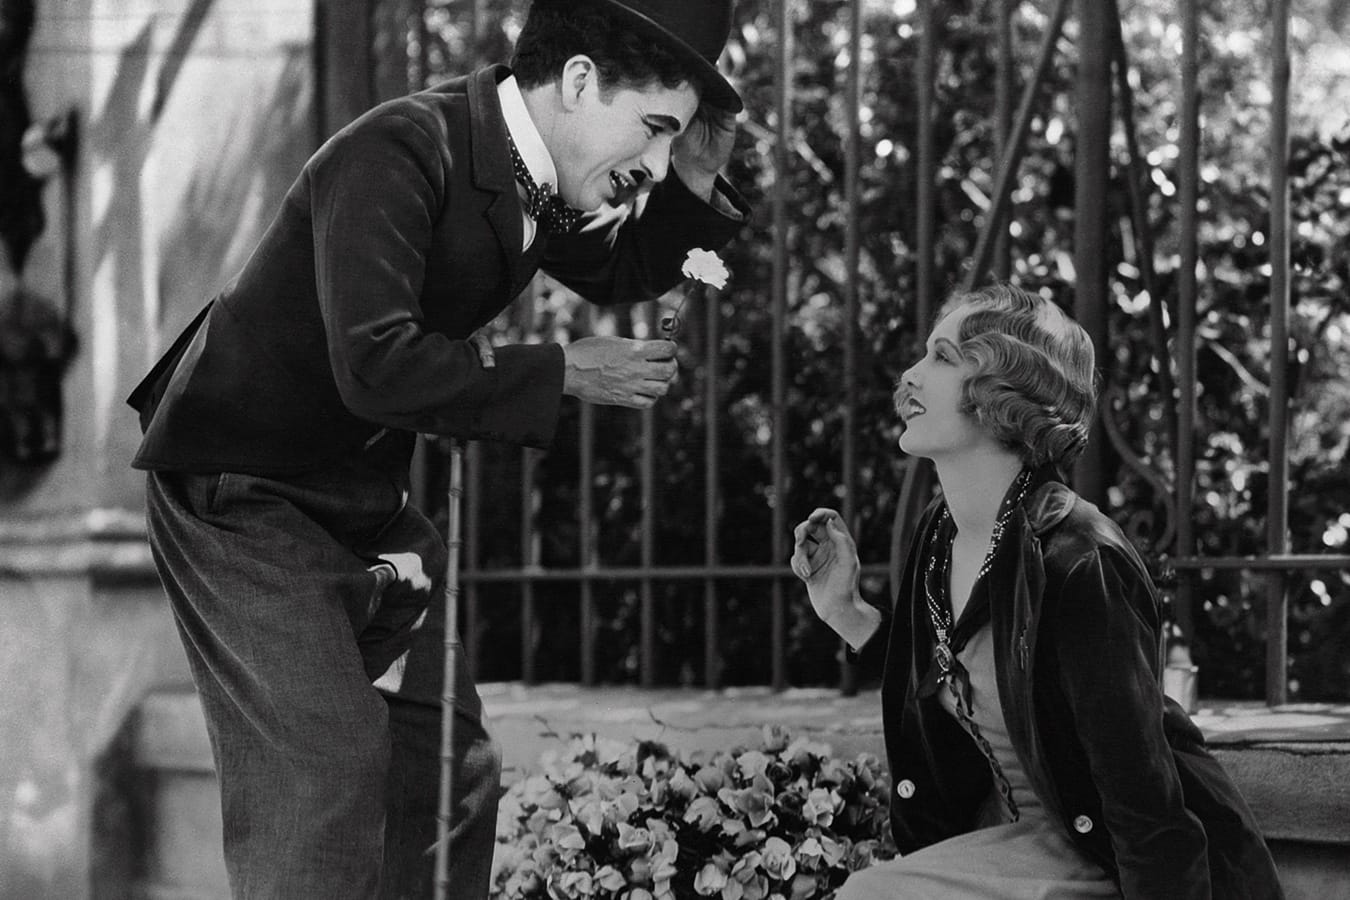
There is an old scene that says what the rest of this section says. In 1919 Charlie Chaplin co-founded United Artists so that the people who made the films would own them. He kept control of production, casting, editing and the negatives, financed City Lights (1931) himself, and earned more than $5m on it.
Buster Keaton went the other way. The General (1926) cost about $750,000 and earned about $470,000, and one failure was enough: by 1928 he had signed with MGM as a salaried employee at $3,000 a week, with no ownership of his work, and his career did not survive the arrangement. Same era. Same talent class. Different contract. Chaplin owned the house. Keaton rented it, and one bad year put him out.
A Korean production company signing a full buyout today is closer to Keaton than to Chaplin. The question this series keeps returning to is whether that has to be true.
Squid Game is where the price got fixed. A script its own industry had turned down for ten years became, within a month of release, the most valuable television series ever made. Everyone reading this knows the numbers. Bloomberg, working from internal Netflix documents, reported that the first season generated approximately $891m in what the company calls impact value, its internal estimate of what a title is worth to the service rather than revenue, against a production cost of about $21.4m, roughly $2.4m per episode.
Executives quoted in the same reporting estimated that the series made in the United States would have cost five to ten times as much. What is less often said is what those numbers did. In the autumn of 2021 they fixed, in the mind of every buyer on earth, what a Korean series is worth to make and what it can return, and the ratio between the two, which inside Netflix has a name, an efficiency score of about 41.7 to 1, has anchored the high end of what a Korean series is expected to deliver ever since.
That measurement happens inside a system Korean producers cannot see. The efficiency score sits alongside adjusted view share and completion rate in the data that decides what gets commissioned next, and the producer who made the show has no contractual right to any of it. The most valuable Korean series ever made established that Korean series are cheap, and its makers were not in the room where that was decided.
The contract that carried the price is the one everyone in the industry knows. Under the cost-plus commission, the buyer pays the full production budget plus a margin, usually 10-20%, and owns everything the show is or becomes. What makes it worth examining is not the mechanism but what it replaced and why it was welcomed. The broadcaster-era deal it displaced looked worse and was, in one respect, better. The broadcaster kept the primary IP and paid a fee that did not cover the budget; the producer carried the deficit and the risk.
But the producer also typically kept 30-40% of overseas sales, and in the first wave of Hallyu, a KRW5bn ($3.7m, at today’s exchange rate) drama that travelled to Japan, Taiwan and Southeast Asia could return KRW2-3bn ($1.5m-2.2m) over two or three years on a KRW2bn ($1.5m) investment. Cost-plus removed the risk and the upside together. It solved the short problem, cash, by selling the long one, and it arrived at the exact moment when the short problem was the only one anybody could afford to think about.